This case research traces the journey of Ethan Brooks, a 45-yr-old undertaking manager at a mid-dimension know-how firm, as he strikes a portion of his retirement savings from a standard 401(k) right into a physical gold IRA. The purpose is to explore the motivations, resolution-making process, implementation steps, and outcomes of a direct rollover into a self-directed IRA that holds physical gold in an IRS-accredited depository. The narrative highlights both the potential advantages and the pitfalls of adding valuable metals to a retirement strategy, whereas underscoring the need for careful due diligence and ongoing monitoring.
Background and motivation
Ethan’s 401(k) was nicely funded, with a balance approaching $320,000. His plan provided a broad array of mutual funds however constrained him to market-linked assets with various levels of volatility. Like many investors, he watched equities swing with geopolitical tensions, inflation readings, and shifting financial coverage. Ethan had lengthy believed in diversification, however he nervous that a heavy publicity to stocks could undermine his retirement targets if a downturn coincided with rising dwelling prices. He had a nascent interest in gold as a possible hedge in opposition to inflation and forex devaluation, bolstered by media reports and a handful of advisor conversations that steered physical gold may present portfolio ballast during periods of monetary stress.
Problem and options evaluation
The central dilemma was whether to stay entirely within the 401(k) framework, switch to a standard IRA, or pursue a self-directed gold IRA that would hold bodily metal. Each option carried tradeoffs. Staying inside the 401(ok) could preserve tax deferral, nevertheless it wouldn’t provide direct possession of physical steel. Moving to a traditional IRA allowed broader autonomy, yet standard IRAs usually do not allow direct ownership of physical gold; instead, they provide exposure by paper belongings or a mix of trust-primarily based products. The self-directed gold IRA introduced a path to precise bodily metal—coins or bars stored in an IRS-approved depository—which was exactly the characteristic that appealed to Ethan as a hedge. Nonetheless, it got here with greater complexity, added prices (hallmarked by setup charges, annual custodial charges, insurance, and storage), and guidelines that required strict compliance, especially round rollovers and depository storage.
Decision course of
After a number of appointments with financial advisors, Ethan narrowed his approach to a direct rollover from the 401(okay) right into a self-directed gold IRA. He favored this route as a result of it avoided the 60-day rollover danger and potential tax withholdings associated with oblique rollovers. The selection also aligned with his need for bodily possession and a clear, insured storage solution. Key issues included selecting an IRS-approved valuable metals custodian, evaluating the forms of eligible metals (comparable to American Gold Eagle or Canadian Gold Maple Leaf coins, and sure gold bars), and selecting an authorized depository for allocated storage. Value transparency emerged as one other priority; Ethan sought a clear breakdown of setup fees, annual custodian fees, storage premiums, and insurance limits.
Implementation steps
1) Deciding on the custodian and depository: Ethan reviewed a number of providers, specializing in those with sturdy reputations for compliance, secure holding facilities, and clear fee constructions. He finally chose a custodian that specialised in self-directed IRAs and offered allotted storage in a Federally insured, IRS-permitted depository. Allocated storage ensured that the precise bars or coins purchased have been attributed to Ethan’s account and held in his name throughout the depository.
2) Initiating the direct rollover: With the custodian chosen, the 401(k) administrator was contacted to initiate a trustee-to-trustee transfer. The rollable portion of Ethan’s 401(okay) funds was directed straight to the precious metals IRA custodian, minimizing tax withholding and avoiding the potential 20% withholding that can accompany indirect rollovers.
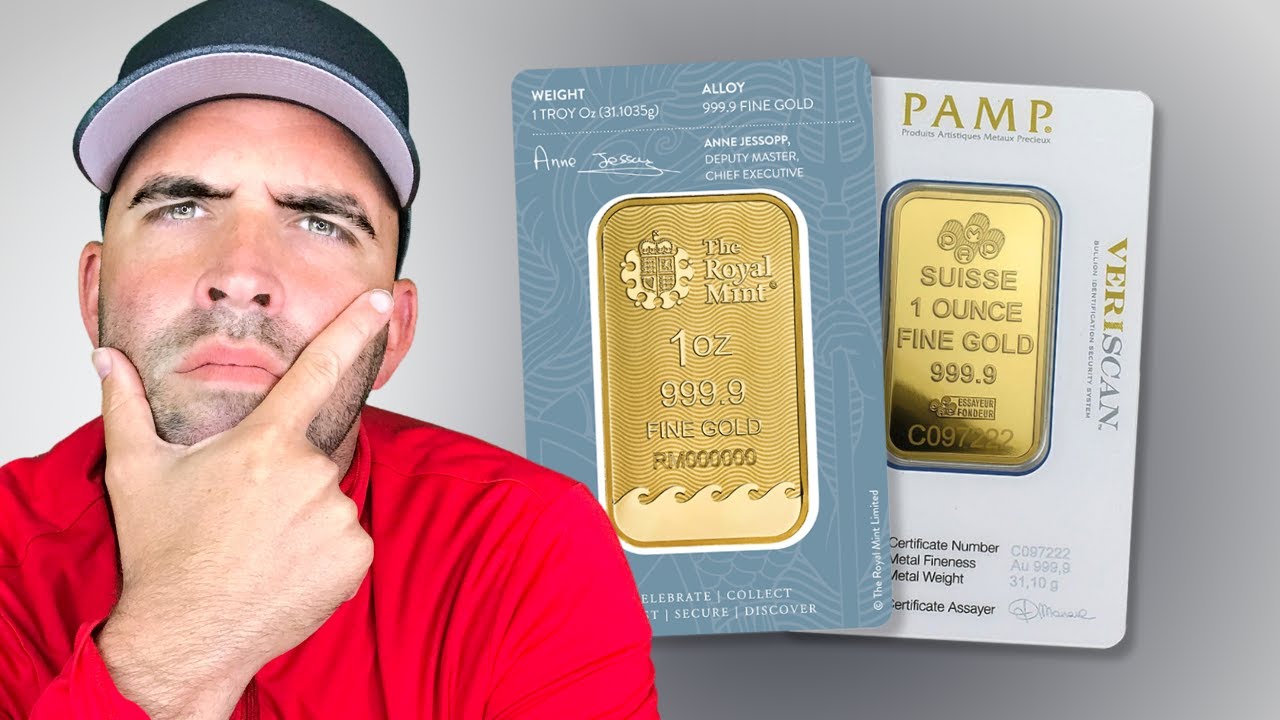
3) Choosing metal type and allocation: The custodian provided steering on IRS-eligible metals and generally accessible choices. Ethan decided to allocate a portion of the rollover into physical gold coins with strong liquid markets (for instance, 1-ounce gold American Eagles) and allowed a smaller allocation to a gold bullion bar within the set of IRS-authorised choices. The goal was to balance liquidity, value, and storage issues whereas sustaining a meaningful inflation hedge. The remainder of the retirement property remained invested in a conventional, diversified mix throughout the gold IRA’s non-metallic holdings or in money equivalents that aligned with the custodian’s threat framework.

4) Storage and insurance arrangements: The gold bought by way of the IRA was stored in an allocated method within an IRS-approved depository. Storage charges various by facility and the diploma of segregation, however they included insurance coverage protection against loss, harm, or theft while the metals remained underneath the IRA’s custodial umbrella. The association complied with IRS guidelines that prohibit holding physical metals exterior the IRA structure, guaranteeing tax-deferred growth remained intact.
5) Compliance and ongoing administration: Ethan signed agreements detailing prohibited transactions, beneficiary designations, and the depository’s audit and reporting schedules. The custodian offered quarterly statements exhibiting valuable metals holdings, unit costs, and storage prices. He also discovered that sure transactions, akin to promoting metals or rebalancing, needed to be conducted via the custodian to take care of tax-advantaged standing.
Dangers, prices, and caveats
- Costs: Direct rollover right into a gold IRA incurs setup fees, annual administration expenses, and storage/insurance coverage costs. Over time, the premium embedded in gold coins and any dealer spread on purchases can affect efficiency. Ethically and virtually, the entire cost of possession in a gold IRA may be greater than a standard equity-based mostly IRA.
- Liquidity and compliance: Physical gold within an IRA shouldn't be as liquid as stocks or ETFs, and the sale course of can take longer because it must be executed by means of the custodian and the depository. The investor must work inside IRS guidelines and the depository’s procedures to keep away from triggers that would jeopardize tax-advantaged standing.
- Market risk: Gold can hedge inflation but doesn't assure positive returns. Its value can move independently of equities, generally in ways that diverge from stock-based mostly efficiency throughout certain economic cycles.
- Storage issues: Allocated storage gives fidelity of ownership but comes at a premium. Unallocated storage may be cheaper but does not assure particular items of metallic are held in Ethan’s account.
- RMDs and withdrawal timing: As lengthy because the property remain inside a retirement construction, withdrawals are taxed as odd income. Ought to Ethan reach distribution age, he would must comply with the usual RMD framework and careful planning to reduce tax impact, conscious that bodily gold carries totally different liquidity characteristics than cash or typical securities.
Outcomes and reflections
Ethan’s first 12 months in the gold IRA did not produce dramatic brief-term shifts in total portfolio worth, but it surely offered a measure of resilience amid episodic inventory-market volatility.